Thomas White
Co-HostSpaceX (SPCX) Earnings Preview: Surging Growth Puts Spending in Focus
Thomas White
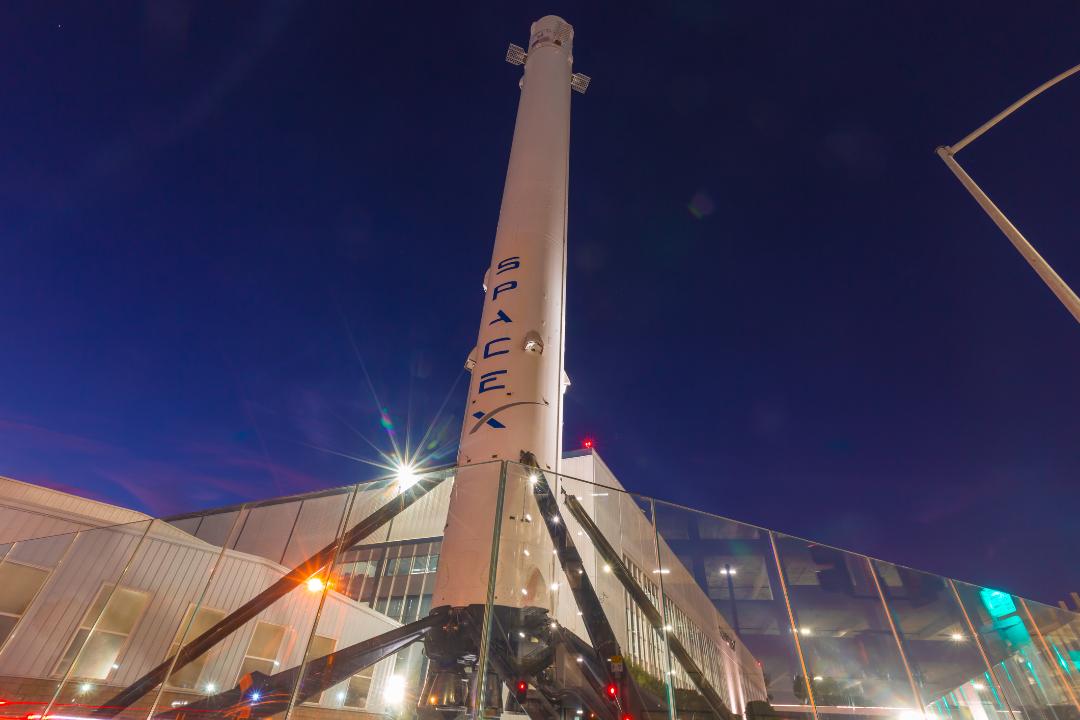
Co-HostSpaceX (SPCX) reports third-quarter earnings Tuesday after the close in its second quarterly release since going public in June.
Investors will weigh rapid revenue growth against an increasingly aggressive capital-spending plan. Wall Street expects roughly $12.9 billion in revenue, up about 65% year over year, and earnings near $0.14 per share. Starlink, Space, and AI will be the key segments to watch.
SpaceX topped expectations last quarter as revenue rose 92% year over year to $7.8 billion and adjusted EBITDA increased 191% to $3.5 billion. Starlink remained the main growth driver, reporting 12 million subscribers and about $4.3 billion in revenue, up 66%, supported by more than 1.7 million net subscriber additions. Enterprise and government revenue grew 108%. Space segment revenue rose 29% year over year to $962 million, while the newer AI business generated approximately $2.6 billion, up 247%.
Capital Expenditures May Draw the Most Scrutiny
SpaceX spent roughly $18.4 billion in Q2, including about $15.8 billion on AI infrastructure. Management expects investment to remain elevated as it funds Starship, next-generation Starlink satellites and AI infrastructure. Separately, SpaceX reported a $143 million operating loss in Q2 despite rapid revenue growth.
Competition is Another Challenge
As SpaceX adds capital-intensive AI infrastructure to its launch and satellite businesses, competition is a challenge. Through xAI, it aims to compete with Alphabet (GOOGL), OpenAI, and Anthropic. In launches, it faces Rocket Lab (RKLB) and Blue Origin, led by Amazon (AMZN) founder Jeff Bezos. Starlink competes for satellite broadband and connectivity customers with Amazon’s upcoming Leo / Project Kuiper and AST SpaceMobile (ASTS).
SpaceX is also preparing to launch a full retail wireless service under the Starlink Mobile brand. This month, it announced multibillion-dollar deals for nationwide low-band terrestrial spectrum, with final regulatory approval outstanding, positioning it to move beyond satellite backup service and become a traditional mobile carrier. That would put it in direct competition with legacy telecom companies, including Verizon (VZ), AT&T (T) and T-Mobile (TMUS).
SpaceX shares have rebounded more than 40% from their early-August post-IPO low but are down nearly 2% this month through Monday’s close of $147.96. The stock remains above its $135 IPO price but well below its record high of $225.64. The Option market is implying a possible +/- 6% move or about $9 on a one-day basis.
Investors will watch Starlink subscriber gains; segment growth; launch and satellite expansion; AI revenue trends; and above all the CapEx outlook. Strong revenue and signs that investment is generating returns could provide optimism for the stock. Another spending surge, without improved operating profitability, could prolong SpaceX valuation and cash-flow concerns.
See the economic and earnings Calendar for the week of Oct. 19, 2026: Week Ahead: Can Corporate Earnings Offset Inflation Risk?
Featured Clips
Buying the Tech Dip: SpaceX, QBTS and Cybersecurity Picks
Opening Bell With Nicole Petallides
► Play video